All Categories
Featured

How to Identify the Medical Health Coverage
Table of Contents
Consider it like the difference in between renting an apartment or condo and owning a home. A traditional, fully-insured plan is like rentingyou pay a set quantity every month, and the proprietor (the insurance company) takes on all the risk and manages all the maintenance. Self-funded and level-funded plans, on the other hand, are more like owning your strategy.
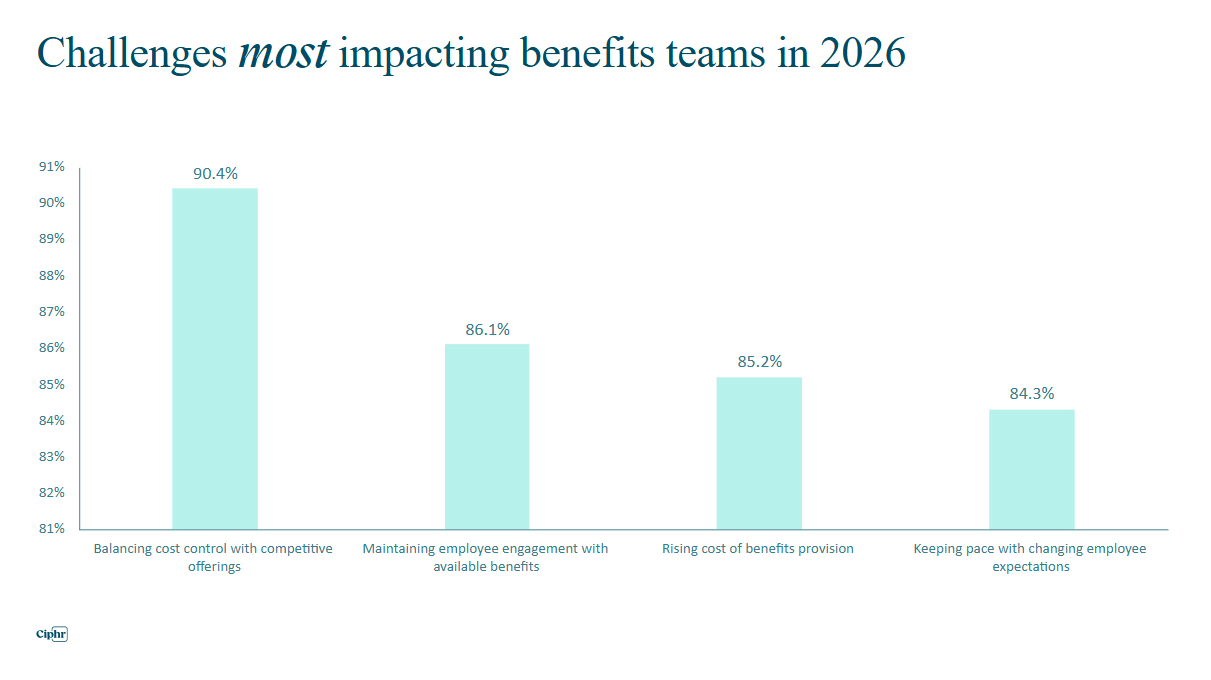
This shift isn't simply a pattern; it's a direct response to the extreme monetary pressure many companies are under. Small companies with Affordable Care Act (ACA)- compliant strategies frequently deal with shocking premium walkings driven by ever-rising healthcare costs. A current survey discovered that the majority of little company owners are deeply worried about price, with many fearing it might hamstring their operations or even force them to drop protection completely.
With a (sometimes called self-insurance), your company stops paying premiums and begins paying for your workers' real healthcare claims straight. That's why companies purchase.
This model opens up 2 substantial advantages: If your group has a healthy year and claims are lower than projected, that cash stays with you. It does not get swiped by an insurance carrier as earnings. You get access to anonymized claims data, which is a goldmine. It reveals you precisely where your health care dollars are going, permitting you to implement health cares that target particular needs and control future costs.
That volatility isn't for every little service. For smaller companies interested by self-funding however worried about the unpredictable money circulation, are a fantastic middle ground.
Enhancing Business Group Incentives and Retaining Talent
Here's how it works. You pay a stable, level regular monthly payment to a third-party administrator (TPA). That single payment packages three crucial things together: An estimate of what's needed to cover your group's medical claims. The expense for that essential devastating protection. The TPA's cost for managing all the claims processing and documentation.
At the end of the year, if your real claims are less than what you paid into the claims fund, you frequently get a refund or a credit for that surplus. This structure gives you the very best of both worlds: foreseeable month-to-month expenses you can budget for, plus a financial benefit if your group remains healthy.
Business Insurance Mission ViejoYou get to take ownership of your healthcare technique and see a direct return on smart, proactive management. What if you could use health benefits by giving your staff members a tax-free allowance to buy their own insurance coverage, instead of selecting a one-size-fits-all plan? That's the huge idea behind a Health Reimbursement Plan (HRA).
This technique puts your employees in the driver's seat. They can choose a specific health strategy from the open market that perfectly fits their individual needs, their family's situation, and their chosen physicians.
Understanding Your Workplace Wellness Program Costs
A QSEHRA lets you repay workers for their private health insurance premiums and other qualified medical costs, approximately a yearly maximum set by the IRS. Because it was created particularly for small companies, there's one secret rule: you can't provide a QSEHRA along with a traditional group health plan. It's an either/or option.

The is a newer and much more flexible choice that works for companies of any size. Unlike the QSEHRA, the ICHRA has, offering you complete control over your benefits spending plan. Even better, you can set different allowance amounts for different "classes" of staff members, like full-time versus part-time or employed versus hourly employees.
A little start-up can begin with a modest contribution and increase it as the company grows. And if your organization becomes an Applicable Large Employer (ALE) with or more workers, a well-structured ICHRA can satisfy the ACA's employer mandate, making it an excellent long-lasting method. To find out more about how HRAs compare to other accounts, have a look at our guide on the differences in between HSAs, FSAs, and HRAs.

The very best choice often boils down to your business's existing size, future development strategies, and just how much versatility you need. Here's a fast breakdown to assist you see the differences side-by-side. Feature ICHRA (Person Protection HRA) QSEHRA (Certified Small Employer HRA) No size limit. Functions for services with 1 worker or 1,000+ staff members.

Latest Posts
Securing Your Business and Group Benefit Solutions
How Local Firms Require Quality Group Coverage
Comprehensive Commercial Insurance and Employee Benefit Advice